The initial interest rate increase in three years has been implemented. The Federal Reserve is now formally taking direct action to curb inflation.
At the same time, this year’s worst-performing equity sector has already been factoring in an economic deceleration. Anyone surprised by the recent agreement on a rate increase clearly hasn’t been monitoring consumer discretionary stocks.
Before the Fed’s decision, the S&P 500 Consumer Discretionary sector had declined 5% year-to-date, significantly trailing the benchmark’s 11% advance. According to Goldman Sachs’ historical analysis, the sector faces further challenges based on previous responses to rate hikes. It dropped an additional 0.7% on Wednesday.
This is understandable given the current environment. Elevated mortgage rates and higher auto-loan and credit-card expenses can reduce households’ financial flexibility for discretionary spending.
However, the sector shouldn’t be viewed uniformly. The weakness hasn’t been universal: Best Buy and Garmin have each risen over 35% year-to-date, with eBay and Ross Stores close behind. Various companies reflect different economic forces that all contribute to the performance of the underperforming consumer discretionary sector.
Let’s categorize the sector’s underperformers into three groups, each illustrating a distinct way higher rates can squeeze discretionary spending:
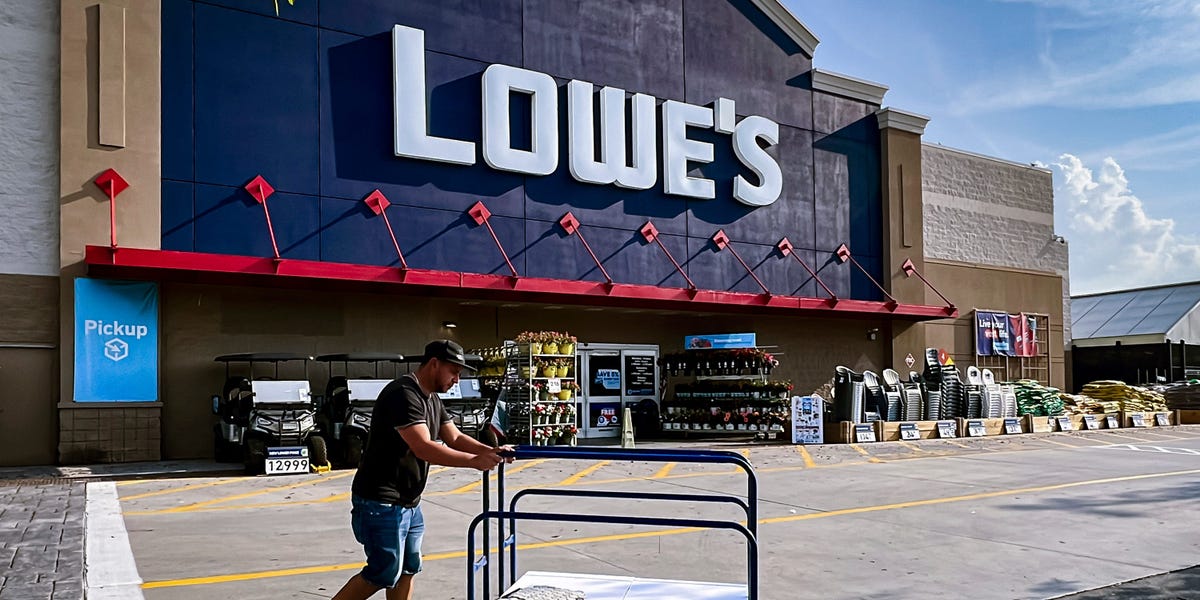
The major purchase test: Lowe’s
YTD stock return: -20%
Lowe’s provides the clearest connection between higher rates and consumer outlays. Major home-improvement projects frequently hinge on a homeowner’s readiness to borrow or access home equity. Increased borrowing costs can make such decisions easier to delay.
This doesn’t mean the home-improvement sector is finished. Repairs to existing homes remain necessary, and Lowe’s has a track record of navigating previous housing downturns.
However, in the AI era, a stable, rate-sensitive business may not deliver the growth narrative investors are seeking.
The premium test: Lululemon and Nike
YTD stock return: -54% for LULU, -44% for NKE
This represents a different consumer calculation. Buyers of these brands don’t require financing, but they’re still paying a premium for products that may be fashionable and well-made — yet ultimately non-essential.
Such retailers can feel the squeeze early when consumers begin retrenching. They may continue spending, but they’re more inclined to switch to lower-priced alternatives.
Naturally, both companies face their own company-specific challenges. Both are undergoing turnaround efforts after extended periods of underperformance. Their stock prices have been pressured as investors assess increasing competition and uncertain growth prospects.
The value test: McDonald’s
YTD stock return: -19%
Unlike the companies above, McDonald’s occupies a unique position. It can serve as a destination for value-conscious consumers. In theory, it should gain as diners migrate from pricier dining options.
Yet its performance still provides valuable consumer insights. If foot traffic starts declining, that could indicate consumers are reducing spending altogether, not just reallocating it more efficiently. If weakness appears in small, everyday purchases, it may truly be time for concern.
Naturally, consumer discretionary doesn’t represent the entire economy. Growth elsewhere can counterbalance one sector’s difficulties. Nevertheless, it can still provide useful clues about the trajectory of the U.S. consumer.
Your guide to what’s driving markets