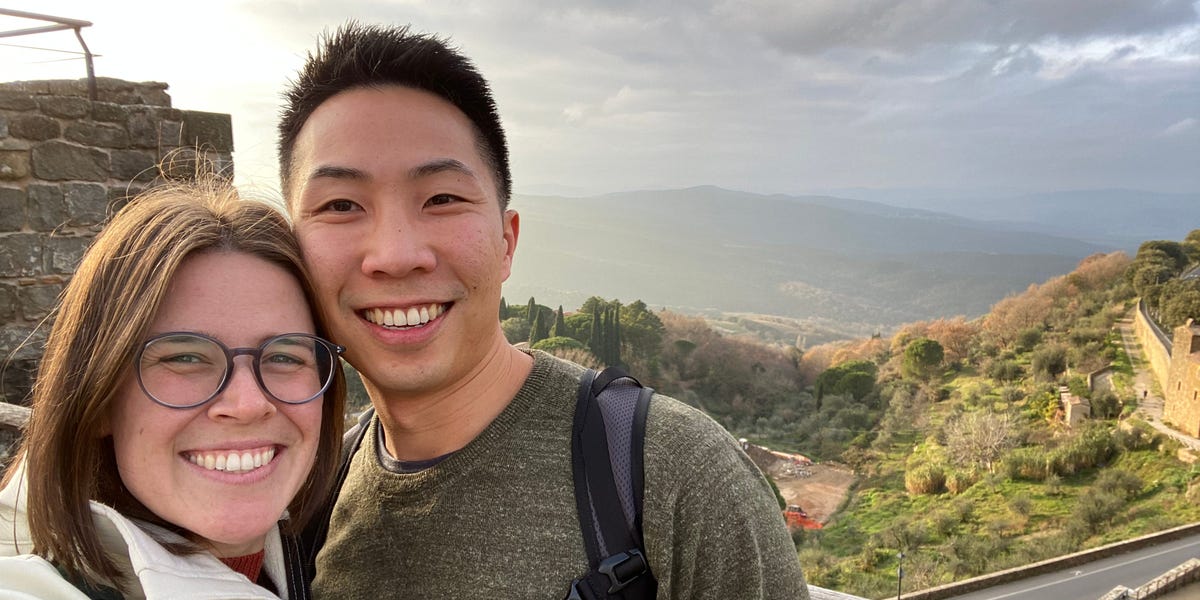
Over a year ago, my spouse and I settled into the living room of the house we once believed would be our “next three decades” residence. We discussed the future and established a target: Before our son begins kindergarten, we’ll relocate to the Netherlands.
Everyone warned us parenthood would shift our priorities, but experiencing the transformation firsthand was still jarring. In late 2024, following the birth of our first child, my spouse and I both harbored the growing sense that the United States wouldn’t be our permanent home.
By the time he first voiced the idea, we shared one of those jaw-dropping moments. We realized we’d independently reached the identical conclusion without ever conversing about it.
It required some time to determine our desired destination. We’ve resided in California throughout our marriage and hesitate to relinquish certain comforts we enjoy here, such as access to quality healthcare and a diverse community.
Nevertheless, there are specific elements we seek in a new home as well, like stricter firearm regulations and an alternative public-education system.
After extensive debate and research, the Netherlands satisfied all our criteria and then some. We visited last year and confirmed it: Relocating here was our objective.
Up to this point, we’d agreed on everything. Then, we began discussing the logistics … specifically, finances.
We’ve consistently held different perspectives on money
When it comes to most matters, my spouse and I can make decisions, reach easy compromises, and act swiftly. However, it took us over a year of marriage — and numerous conversations — to feel comfortable combining our bank accounts.
My spouse is highly financially literate and somewhat money-obsessed. Meanwhile, I’ll deposit money into our savings account and promptly forget about it.
He’s captivated by business, holds strong opinions on investing, and consistently reassesses our broader wealth-building strategy. I benefit immensely from his fascination with finance, since none of this is my forte.
Our goal to move to the Netherlands has thrust us into one of the more complex financial discussions we’ve had in a decade of marriage. It distills to a fundamental disagreement: He wants to accumulate wealth first, then relocate. I want to relocate, then resume accumulating wealth.
He views the Netherlands as a finish line. I see it as our next starting line.
He wants to ‘retire’ to the Netherlands, but I want to begin anew
We intended to move to the Netherlands through the Dutch-American Friendship Treaty (DAFT), which permits an entrepreneur to transfer a small business to the Netherlands and work toward residency.
However, purchasing a home appears difficult without a full-time position with a Dutch employer. The alternative, the rental market, is challenging too. Some leases require expats to pay a full year (or two!) of rent entirely upfront.
According to my spouse, there’s an obvious “optimal” plan: save sufficient money here in the US so we can purchase a house, with cash, in the Netherlands.
Now, we have a young son, and we’re expecting baby number two. A livable apartment for a family of four would cost anywhere between 450,000 euros and 600,000 euros. In USD, this would mean we’d easily be spending over $500,000 at the low end — likely considerably more.
We manage our finances well, but we don’t possess that kind of capital. And between our current mortgage, the cost of childcare for two children, and the general high cost of living in Northern California, it’s difficult to envision that changing over the next two or three years.
My proposed solution? We move now and begin as renters. A full year of rent for a livable two-bedroom apartment in the coveted Ramstand area of the Netherlands would run us about 24,000 euros, or roughly $28,000.
This way, we could continue building our wealth in the Netherlands. Leap, and figure it out as we go.
That uncertainty terrifies my spouse, who doesn’t want to start from scratch. I understand his perspective: We’re comfortable right now. He’s earning a healthy income. He’s afraid of abandoning this life and ending up worse off.
If we leap and rent, we’re landing without jobs. However, I believe we’ll work it out.
We’re still determining our plans — and progressing toward our end goal
We’ve talked until we’re both exhausted. Our current approach is two-fold: save as much as possible here in the US, and apply aggressively for positions in the Netherlands. The two paths forward aren’t mutually exclusive, so we’ll pursue both.
Our reasoning is that, with time, one of us will either secure a job that will allow us to qualify for a Dutch mortgage and purchase a home with a loan, or we’ll accumulate enough cash here in the US to buy a Dutch home outright.
Two routes, two distinct financial strategies, and two potentially very different timelines for relocating. We have three years to achieve our goal of moving before our son starts kindergarten, and we hope one of these strategies will enable us to do it.
Did I mention that I’m pregnant and we have a toddler? It’s going to be a hectic few years, but we’re enthusiastic.