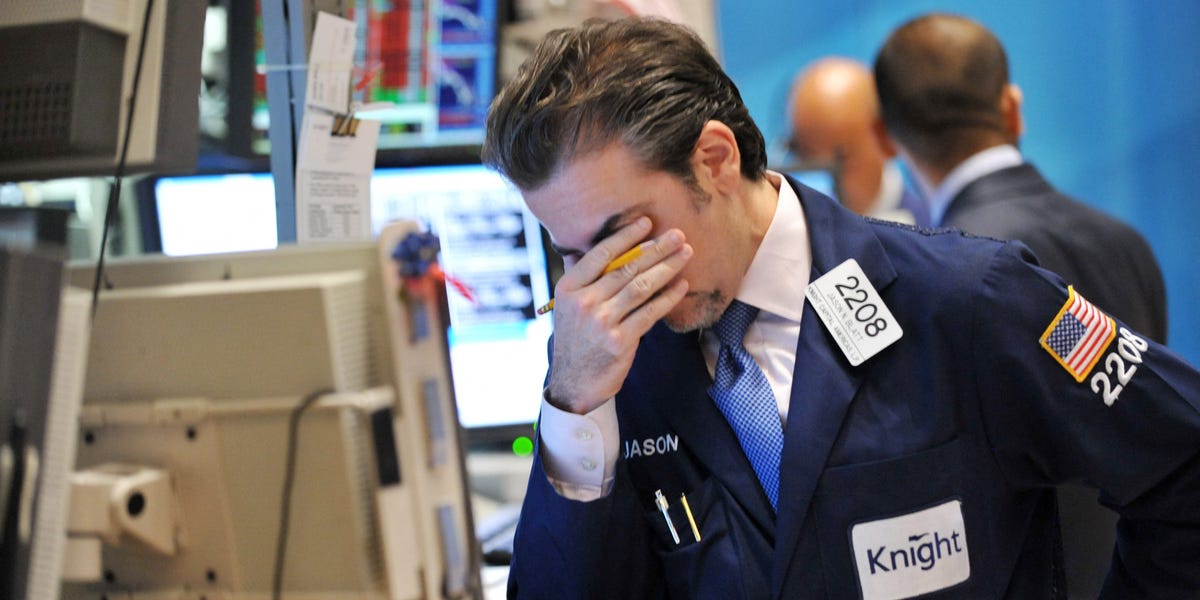
Long-term bond yields are once again pressuring stocks, and BNP Paribas indicates the situation is likely to deteriorate further. In a client note released on Tuesday, the financial institution projected that yields on the 30-year Treasury bond could ascend to 5.6% in the upcoming months. As of Thursday afternoon, yields were recorded at 5.43%, a significant rise from 4.83% at the beginning of the year. It is important to note that when yields increase, bond prices correspondingly decrease. Elevated long-term bond yields typically exert a drag on stock performance, as investors juxtapose the risk-free returns of Treasuries against anticipated earnings yields. The recent surge in yields has been fueled by climbing oil prices and resultant inflation anxieties, apprehensions regarding the expanding government debt, and substantial borrowing demands from both governmental entities and artificial intelligence hyperscalers. BNP Paribas’ expectation for continued upward pressure on rates is rooted in growing debt concerns, with the bank identifying three imminent catalysts that could amplify market skepticism. The initial factor is the Federal Reserve’s ongoing rate-hike cycle. The central bank implemented a 25 basis point increase in September and is poised for potential additional hikes in 2026, with another possible adjustment by April 2027. This action is set to markedly elevate the interest obligations on US government borrowing, as the Treasury predominantly accesses funds through the short segment of the yield curve, according to BNP. Guneet Dhingra, the head of US rates strategy at BNP, stated in the note that if the Federal Reserve proceeds with the four hikes factored into market pricing, the Treasury’s interest burden will augment by $116 billion in the first year and approximately $168 billion by the second year. For comparative purposes, a $168 billion increment in interest expenses would completely negate all the additional tariff revenues generated in 2025. The second catalyst involves the government’s budget deficit, which is beginning to widen anew. This expansion is attributable to tariff rollbacks and refunds, coupled with recent increases in long-term interest rates, thereby establishing a self-perpetuating feedback mechanism. Thirdly, investors may be underestimating the government’s fiscal expenditure intentions following the US midterm elections. With the Democratic party anticipated to reclaim the House of Representatives, or potentially both the House and the Senate, BNP Paribas suggested that spending might be expected to diminish due to anticipated reduced synergy between the executive branch and Congress. However, this assumption could be erroneous. A similar electoral outcome after the 2018 midterm elections resulted in sustained high spending levels, as observed by the bank. Furthermore, defense spending is projected to escalate, with the bipartisan Senate Armed Services Committee having already sanctioned a $250 billion augmentation to the defense budget. In light of these fiscal risks, Dhingra concluded that the most probable trend remains an upward trajectory for longer-term yields.
Trending
- Meta’s agentic AI push with Muse feels different after a history of disrupting tech
- Following My Oracle Layoff in March, the Job Hunt’s Biggest Obstacle is Human Review
- Battle of the brands: Two AI startups clash over the ‘Soar’ name
- This consulting firm is making bespoke AI apps to replace the PowerPoint pitch
- Three catalysts that could deepen the bond market sell-off
- Artificial intelligence isn’t ready to handle your holiday gift buying, fresh research indicates.
- How Mike Burnett Turned Trend-Spotting Into an 8-Figure Business
- McDonald’s $8.5 Billion Restaurant Revamp Fails to Win Over Investors as Stock Falls to Four-Year Low
Friday, September 25