Citi becomes the newest non-Madison Avenue firm to debut an advertising operation.
The bank disclosed exclusively to CMO Insider that it’s establishing a new division named Citi Commerce Media, enabling brands to reach its 70-million-plus customers through spending-based targeting.
Citi will serve ads to users on its proprietary app and website, plus third-party platforms, leveraging transaction histories. For example, a Facebook user might encounter a 10% discount offer from a travel brand.
Central to Citi’s value proposition is the ability to tie advertisements to quantifiable business outcomes. The company reported a pilot involving retail, payments, tech, and health-and-beauty advertisers, where two campaigns delivered an average 15% increase in spending versus unexposed groups.
Citi stated its platform draws insights from 6.5 billion yearly transactions spanning over 700 spending categories.
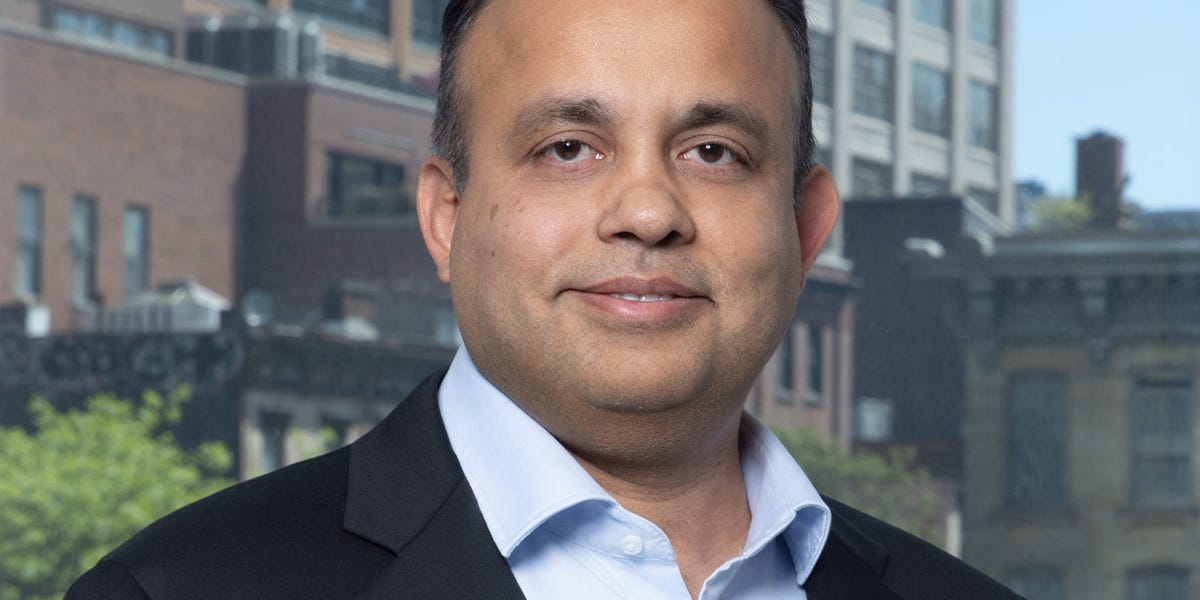
“Our focus centers on spending patterns, which is what advertisers prioritize most,” said Abhinav Anand, who leads value cards, lending, and commerce at Citi.
An expanding roster of non-advertising enterprises are monetizing customer data to build ad businesses. Citi exemplifies the rapidly growing financial media network sector, where firms harness first-party data to let advertisers target audiences across the digital landscape.
As financial institutions, they possess a more comprehensive view of customer spending than conventional retail media networks — typically grocers or big-box retailers like Walmart — which target ads based on browsing and purchasing within their own ecosystems.
Anand sees an opening to capture ad spend from retail media networks with narrower data sets.
EMARKETER, a Themoneytimes sister company, projects financial media networks will exceed $1 billion in U.S. ad spend by 2026 and expand at a compound annual growth rate above 66% through 2027.
Other financial players have already launched similar networks. JPMorgan Chase and PayPal debuted ad businesses in 2024, while Mastercard and American Express followed suit in fall 2025.
For traditional banks, these networks represent a fresh revenue stream as fintechs and buy-now-pay-later providers such as Klarna and Affirm eat into their territory.
Citi enters a crowded marketplace
Anand conceded Citi is entering a competitive arena.
He expressed little concern about not being first, citing Citi’s massive credit-card customer base, and noted earlier movers proved market demand exists.
Citi anticipates a lift from Kard, a commerce, media, and rewards platform it recently agreed to acquire. Kard provides Citi a ready-made merchant base for ad sales. Anand also highlighted a feature letting advertisers target consumers at various purchase-cycle stages.
Kasha Cacy, chief media officer at agency Known, said Citi’s late arrival isn’t necessarily a disadvantage if it launches with a strong sales operation.
“Citi should have substantial purchase-behavior data — perhaps not at Amazon’s scale but still significant — and if you can target based on that, it could be a compelling alternative to Amazon,” she said.
Risks accompany this venture. Given the depth of customer data financial firms hold, moving into advertising demands transparency about data usage. Citi customers must opt out to avoid these ads.
Anand said Citi designed its platform with data privacy and trust as priorities, serving personalized, contextually relevant ads.
“We’ve built our business on Citi’s longstanding reputation as a trusted financial advisor,” he said. “We’re carrying those principles forward. The ads and offers you’ll see in the Citi ecosystem will be highly tailored to you, not randomly served.”