The most recent employment figures may have delayed the next Federal Reserve rate increase. Markets operated in “bad news is good news” mode Friday after a softer-than-anticipated September jobs report. The economy generated only 29,000 positions, significantly missing forecasts of approximately 90,000 new jobs, while the unemployment rate unexpectedly rose from 4.1% to 4.2%.
This appears negative on the surface, until considering the calculation investors have been making since the Fed initiated its rate-hiking cycle this year. A cooling labor market implies the central bank may lack room to aggressively raise rates, which benefits risk-asset valuations.
Combined with a favorable personal consumption expenditures reading on Wednesday, the latest employment data has prompted traders to rapidly adjust rate expectations, with bond yields declining sharply Friday while US equities advanced.
Markets now assign an 83% probability that the Fed will maintain rates at their October policy meeting, according to the CME FedWatch tool. The odds of rates remaining unchanged through year-end also increased to 25%, up from 7% last week.
The benchmark 10-year US Treasury yield dropped as much as 6 basis points to 5.17% as investors processed the data. The 2-year Treasury yield, most sensitive to Fed rate expectations, also fell up to 6 basis points to 4.72%.
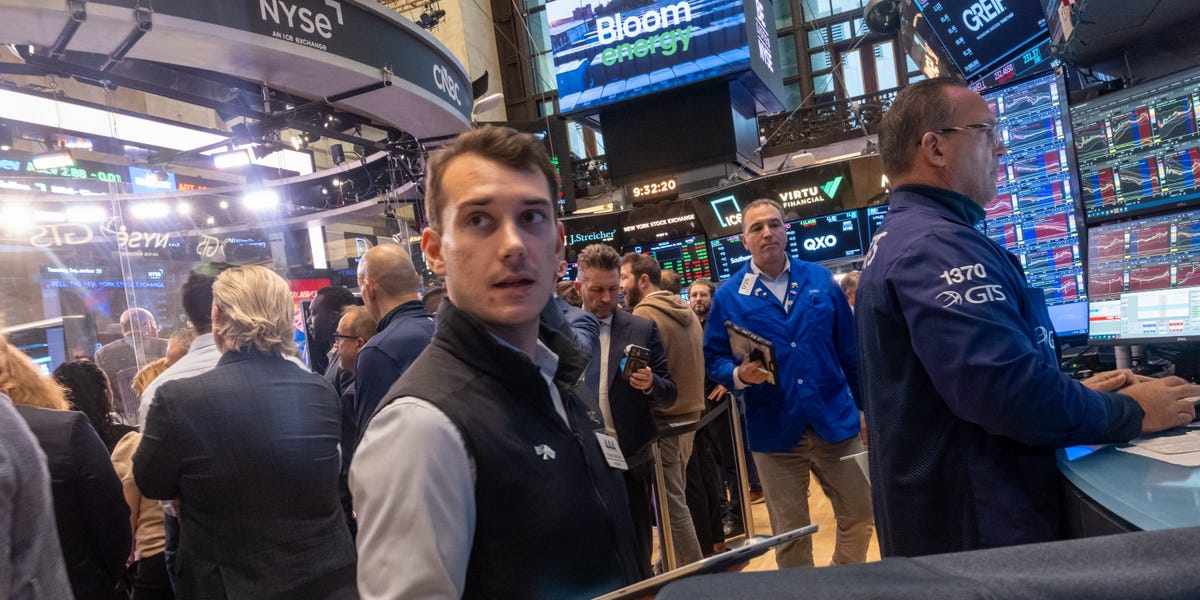
Major stock indexes rallied, recovering some losses from the previous week as the yield spike had unsettled investors. The Dow Jones Industrial Average jumped 500 points, while the tech-heavy Nasdaq gained over 1%.
Here’s where US index futures stood around 10 a.m. ET:
– S&P 500: 7,732.01, up 0.86%
– Dow Jones Industrial Average: 51,176.82, up 0.5% (+250 points)
– Nasdaq 100: 30,912.43, up 1.35%
Investors enthusiastically bought tech stocks. The sector, which has masked broader market weakness recently, has risen amid growing optimism for AI agents and continued excitement for major IPOs from AI leaders like Anthropic and OpenAI.
Notable movers on Friday:
| Company | Ticker | Friday’s gain |
| Advanced Micro Devices | AMD | +3% |
| Nvidia | NVDA | +2% |
| Meta | META | +1% |
| Microsoft | MSFT | +1% |
| Micron | MU | +1% |
| Broadcom | AVGO | +1% |
“There is zero chance for a rate hike in October now—in retrospect, September should have been a hold. Outside of energy, the inflation impulse is lower, and Fed was zigging when it should have been zagging,” Jamie Cox, managing partner at Harris Financial Group, said in a note.
“A softer-than-expected jobs report should put an October Fed hike firmly on the back foot,” Seema Shah, chief global strategist at Principal Asset Management, said. “That should take some steam out of Treasury yields and reduce the urgency for the Fed to act.”
Investors now await September’s consumer inflation report on October 14, the next key datapoint for the Fed as it determines monetary policy through year-end.
“This report strengthens the case for the Federal Reserve to remain patient. The labor market has not deteriorated sharply, but there is also little evidence that it has meaningfully strengthened, giving policymakers reason to wait for additional data,” Adam Schickling, senior economist at Vanguard, said.
Economic data has been mixed recently. Before the cooler jobs data, bond yields surged last week partly due to data indicating strong US growth, with business activity expanding at its fastest pace in over five years last month, according to S&P Global.