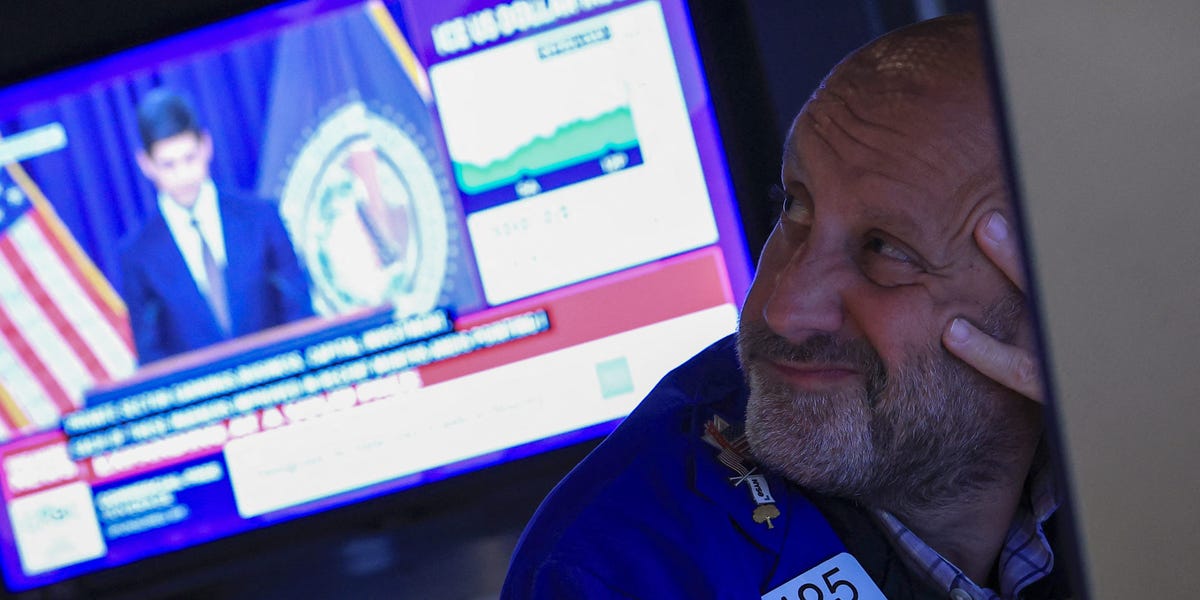
The Fed provides updates on interest rates every month or two. However, investor expectations about the central bank’s next move can change in less than a day.
This week serves as a prime example. Prior to Tuesday, investors were pricing in a 70% likelihood of an October rate increase. But in the afternoon, New York Fed President John Williams indicated the bank might wait until December. The probability plummeted.
Fast forward to Wednesday morning, when the Fed’s preferred core inflation metric came in cooler than anticipated, weakening the case for an immediate rate hike. By day’s end, the odds of an October move had dropped to 37%.
The entire episode unfolded over approximately 18 hours.
Now, the jobs report arrives
As if investor expectations hadn’t already been turbulent this week, tomorrow’s September jobs report is imminent. With rate-hike probabilities shifting so dramatically, the script for what traders should anticipate has been rewritten.
Let’s examine several scenarios and the most probable market reactions to each:
– Strong jobs/wages data: October rate hike odds rebound, short-term yields increase, and stocks likely decline as investors prepare for another round of higher rates.
– Weak report: A Fed pause appears more likely, short-term yields decrease, and stocks probably rise on the prospect of a less hawkish Federal Reserve. Concerns about an economic slowdown may persist.
– Middle ground: The Fed gains flexibility to wait, short-term yields moderate, and stocks likely rise as the soft-landing narrative gains renewed traction. This outcome is most favorable for investors.
The market’s primary challenge persists
However, there’s a complication. None of these outcomes necessarily resolves the bond market’s most significant problem—one that transcends the Fed’s immediate actions: elevated long-term yields, which are already at multi-decade highs. These are the rates that affect mortgages, credit cards, and auto loans.
Long-term Treasury investors aren’t solely focused on whether the Fed raises rates in October or December. They’re considering Washington’s massive deficits and the growing supply of government debt, along with the risk that inflation remains stubbornly high. Add the debt-fueled AI expansion to the mix, and investors are demanding substantial compensation to lock up their money for the next few decades.
Want more Themoneytimes in your news feed?
Add BI in Google so our reporting is easier to find when you’re searching for what matters.
The Fed won’t be able to fix that—certainly not with a single meeting still four weeks away. If policymakers skip an October hike and long-term yields still refuse to decline, don’t say you weren’t warned.
Your guide to what’s moving markets