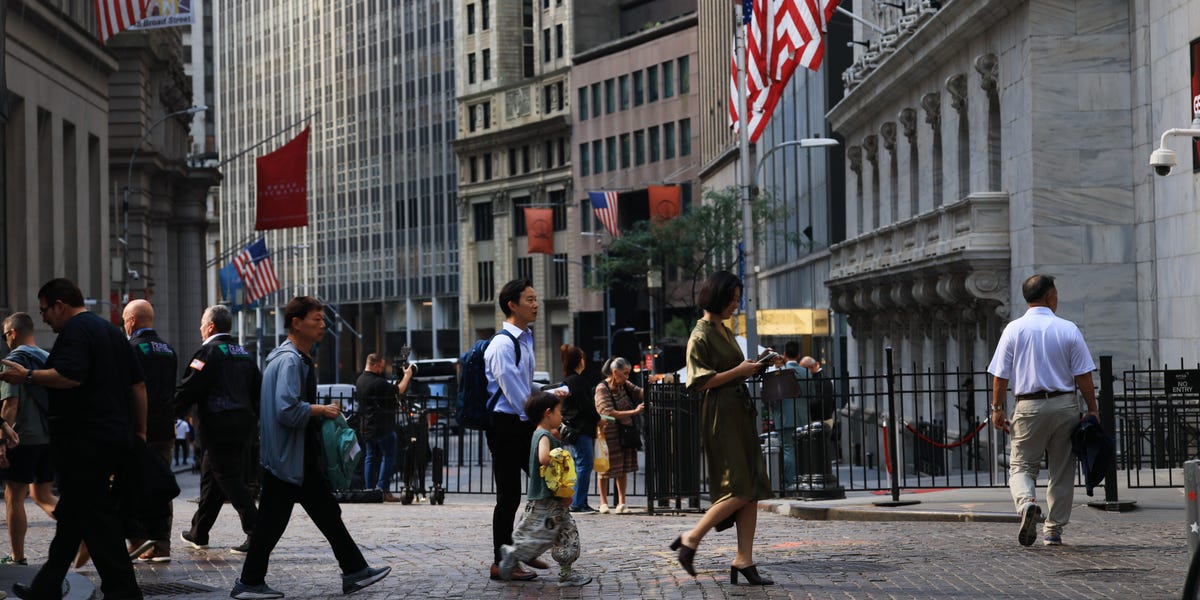
AI-related pessimism is compounding an already turbulent array of market pressures weighing on equities this week. The timing of recent AI cautionary statements from leading executives couldn’t be more inopportune. Investors are simultaneously grappling with escalating oil costs, persistent increases in bond yields, and the strong possibility that the Federal Reserve is poised to implement a rate increase at its upcoming policy meeting.
Calls from Anthropic CEO Dario Amodei and OpenAI CEO Sam Altman to decelerate AI progress echo last week’s warnings about the existential threats posed by the technology. This abrupt shift toward restraint, following years of intense competition among firms to escalate AI investments, represents a dramatic change in sentiment that triggered a stock market decline on Monday.
Semiconductor stocks bore the brunt of the downturn. Overnight losses in Asian markets were led by South Korean memory chip leaders SK Hynix and Samsung, which fell 6% and 5%, respectively. The downward trend persisted into U.S. trading sessions.
Here’s how major U.S. indices looked shortly after the 9:30 a.m. ET market open:
– S&P 500: 7,615.16, down 0.55%
– Dow Jones Industrial Average: 52,424.38, down 0.28% (-148.91 points)
– Nasdaq 100: 28,996.28, down 1.27%
Concerns began mounting last week when Anthropic researcher Jacob Coxon gained attention online after announcing his departure and cautioning that AI researchers are essentially “gambling with our lives.” He highlighted growing anxiety within the industry about the potential for the technology to pose an existential threat to humanity by the decade’s end.
Additional researchers voiced similar concerns, prompting Anthropic CEO Dario Amodei to advocate for a slowdown in the industry over the weekend. OpenAI CEO Sam Altman echoed these sentiments in a subsequent post, suggesting that the company’s highly anticipated IPO this year might now be “ill-advised.”
On Monday, Microsoft took steps toward curbing rapid AI advancement by releasing a preliminary code of ethics designed to establish boundaries for developing next-generation AI models.
Notable movements in the technology sector included:
Beyond rising AI anxieties, markets were already confronting a triple threat of challenges that jeopardize the bull market’s momentum heading into autumn.
– Energy prices are climbing again. Oil prices continued rising on Monday due to renewed conflict in the Middle East and news of Saudi Arabia shutting down a pipeline that circumvents the Strait of Hormuz. Brent crude, the global benchmark, jumped another 4% to exceed $109 per barrel. West Texas Intermediate crude also increased 4% to $104, stoking concerns about inflationary pressures.
– The bond market is experiencing a sharp sell-off. Yields have surged in recent weeks as elevated energy costs push investors to anticipate higher interest rates. Market participants have also been divesting from Treasurys amid lingering concerns over the U.S. fiscal outlook. The yield on the 10-year Treasury note remained near 4.98% on Monday, approaching the critical 5% mark. A $6 billion repurchase of long-term Treasurys did little to quell the selling pressure.
– A Federal Reserve rate hike now appears almost inevitable. Market expectations indicate a 90% likelihood that the Fed will increase borrowing costs by 25 basis points at its policy meeting this week, up from a 33% chance a month earlier, as shown by the CME FedWatch tracker.
Cracks are starting to emerge in the bull market, according to prominent economist David Rosenberg. He noted that the S&P 500 has declined 1% over the past month, while the Dow and Russell 2000 are trading below their 50-day moving averages—a key technical indicator reflecting short-term price momentum.
Market breadth, which measures the proportion of advancing versus declining stocks, is also showing clear signs of deterioration, Rosenberg added.
“In any case, we’ve entered a new phase in this narrative,” he wrote regarding the AI investment trend, referencing related challenges such as climbing bond yields. “With the exceptionally high correlation across all S&P 500 sectors to the tech trade—excluding Health Care and Consumer Staples—one can reasonably expect the ‘bullish breadth’ thesis to reverse.”
The immediate reaction to AI-related fears comes at a moment when the tech sector is already significantly weakened, according to analysts at Jefferies in a Monday report, highlighting the fact that the iShares Semiconductor ETF had fallen 20% from its recent peak. The fund dropped another 5% Monday morning.
In a separate Monday note, Bank of America modestly raised its year-end forecast for the S&P 500 to 7,400, though the updated projection still suggests roughly 3% downside from current levels.
“There will likely be a better entry point for the S&P 500,” the analysts wrote. “The 1970s offers parallels to today—upside inflation risk, dollar depreciation, Fed tightening, and an oil embargo—which preceded a bear market that resulted in a 40%+ drop in stock values and P/E ratios contracting from 19x to 8x.”
All focus is now on the Fed’s interest rate announcement scheduled for Wednesday afternoon. Investors will be closely listening to Fed Chair Kevin Warsh’s comments following the policy meeting, which may provide valuable insight into the central bank’s perspective on inflation and other economic factors influencing financial markets.
This article was originally published on Themoneytimes.