The worldwide bond market is experiencing a troubling period.
Government yields have been rising steadily for months, and investors, tired of poor fiscal management, are demanding higher returns.
Governments face a challenging combination of inflation risks, huge borrowing requirements—such as funding a war in Iran—and debt‑financed corporate expenditures, largely on AI.
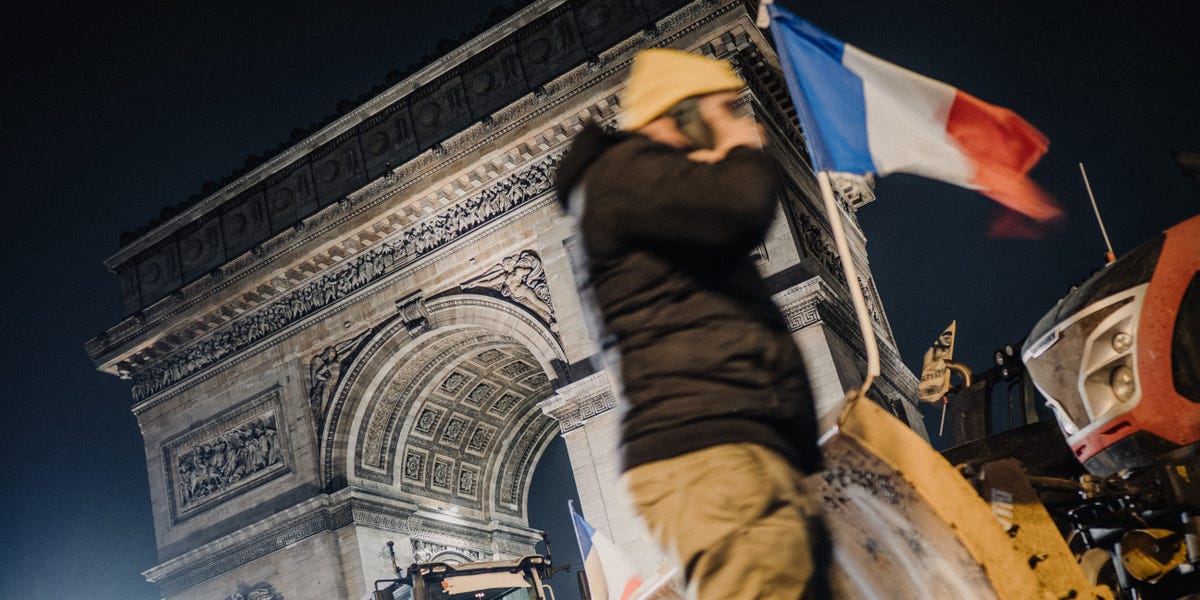
The usual suspects— the United States and Japan—are involved, yet France has emerged as the starkest illustration of what occurs when investors no longer assume a large, wealthy nation automatically receives the benefit of the doubt.
Before examining why France is facing this unwelcome spotlight, consider the financial fallout: the yield on France’s 10‑year government bonds recently reached its highest level since 2002, surpassing even the peak seen during Greece’s crisis.
Even more striking is how quickly it attained that level. While fiscal worries have been growing across Europe—in the UK, Italy, Germany, and others—France has distinguished itself.
In fact, the situation has deteriorated so rapidly that the spread between French and German debt is now at its widest point since the euro‑zone debt crisis about ten years ago.
Why France’s case stands out
France faces numerous fiscal challenges: a large debt burden, a sizable annual budget deficit, modest growth, and now significantly higher interest costs. Each issue alone might be manageable, but together they can quickly destabilize the country’s debt.
France lacks the safety net enjoyed by the United States or Japan. The U.S. issues its own currency, which serves as the global reserve currency, while in Japan a large portion of government debt is held by domestic investors. France does not benefit from comparable protection.
And then there is the political dilemma facing the country:
– If it cuts spending, ongoing protests could expand, and near‑term economic growth could slow.
– If it keeps spending, it will continue to borrow at increasingly punishing rates.
– If it raises taxes, it would risk slowing an already‑sluggish economy.
In short, France lacks a straightforward solution to its predicament, and a potentially destabilizing presidential election is approaching in 2027.
Why Paris matters to Main Street
To be clear, the United States is not France. It possesses its own currency, the world’s deepest government‑bond market, and can count on seemingly endless demand for Treasurys.
Nevertheless, the French episode reminds us that markets can rapidly reprice a government’s finances once confidence erodes. The United States also contends with large deficits, rising interest costs, and political deadlock over tax increases or spending reductions.
Although rising French yields won’t directly lift U.S. mortgage rates, they reflect a broader global increase in borrowing costs. The fixed‑income market is interconnected, so pressure from France could spread abroad. Moreover, a European flare‑up could unsettle stocks, strengthen the dollar, and drive investors toward safe‑haven assets.
France is far from imminent default, but its bond‑market turmoil serves as a useful reminder that fiscal credibility can vanish far more quickly than it is earned. Hopefully Washington is taking note.
A guide to what’s moving the markets