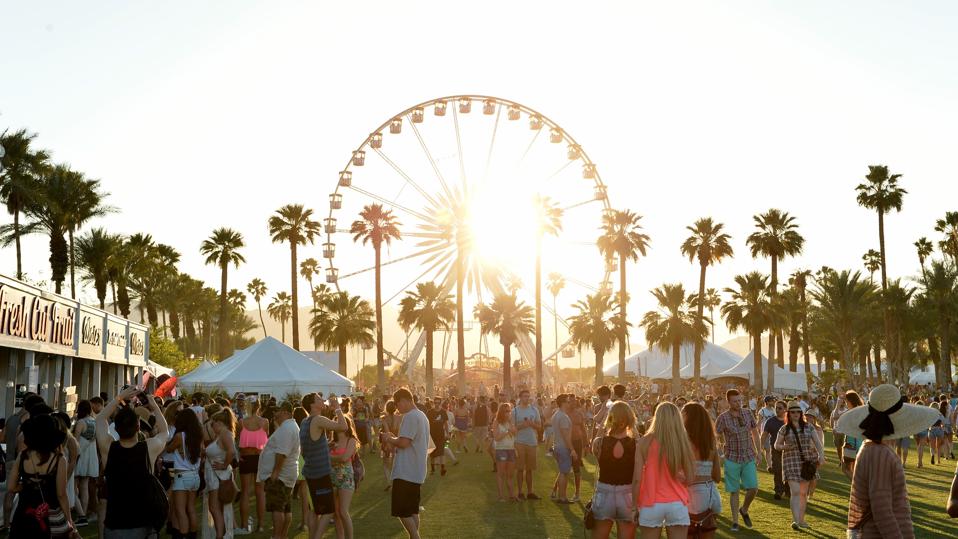
This year, Coachella wasn’t just a showcase for the biggest names in music. It was a flashpoint in the growing tension between fintech innovation and financial literacy. When festivalgoers revealed they had used Buy Now, Pay Later (BNPL) services to cover the cost of tickets, social media lit up with finger-wagging commentary, viral headlines, and plenty of moral panic. Meanwhile, DoorDash quietly rolled out a similar installment option, signaling just how quickly BNPL has become embedded in everyday spending.
But the real question isn’t whether BNPL is being overused. It’s why so many people feel the need to rely on installment plans for basic expenses in the first place. That’s not a payments problem. It’s a system problem, rooted in the fact that millions of Americans have never been taught how to navigate credit, debt, or financial decision-making with confidence.
BNPL Isn’t the Issue, Misunderstanding It Is
The past two decades of payments and fintech innovation show how the right technologies can expand access, improve transparency, and offer greater financial flexibility—especially for consumers underserved by traditional credit models.
BNPL, when done right, is one of those innovations. It’s not inherently risky or irresponsible. It’s simply a tool—one that, for many users, offers clearer terms and better short-term control than payday loans, for example. But like any financial product, it requires informed usage.
Unfortunately, the average consumer is far from equipped. According to a 2023 TIAA Institute study, U.S. adults answered only 48% of financial literacy questions correctly, and only 18% could handle questions related to risk. That’s a national failure. As we mark National Financial Capability Month—aka National Financial Literacy Month—this should worry regulators far more than whether someone financed a festival wristband.
The Real Risk: Meeting Consumer Confusion with Judgment
The backlash we’re seeing against BNPL, and against the people using it, is rooted in a dangerous assumption: that financial tools should be foolproof. That if a product can be misused, it shouldn’t exist.
By that logic, we’d need to eliminate student loans, even mortgages. But we don’t. We expect people to navigate them with minimal education and support. That’s precisely the problem, and exactly why financial literacy needs to be treated as a foundational skill, not an afterthought. BNPL should be no exception.
The reality is that when confusion is met with judgment instead of guidance, we widen the trust gap between financial institutions and the communities they serve.
Regulation Alone Won’t Solve This
Let’s be clear: smart regulation is always welcome in this industry. Transparency, responsible underwriting, and clear disclosures should be the baseline for every fintech offering—BNPL or otherwise. Providers have a duty to act in good faith, especially when serving younger or underserved consumers.
But regulation isn’t a substitute for education. Nor should it become a bludgeon that stifles innovation. The U.S. financial regulatory framework is already struggling to keep up with technology. What we need is a more collaborative model, one that brings regulators, fintech leaders, educators, and consumer advocates together to design solutions that work in the real world.
The finance industry could start by treating financial literacy the same way we teach driver’s education: essential, standardized, and required before taking the wheel. Empower people to ask better questions, and we’ll get better answers.
BNPL Can Be a Catalyst, Not a Cautionary Tale
There’s a healthier, more constructive path forward, and BNPL can be part of it. When installment solutions are built on existing cards, offer zero or low interest, and include transparent repayment structures, they become a bridge—not a trap.
More importantly, they can become an entry point into deeper financial capability, if we build the right educational scaffolding around them. That’s where regulators, fintech platforms, and educators must work in lockstep: not to eliminate risk, but to equip consumers to understand it.
So instead of judging consumers for using BNPL to see Travis Scott or Lady Gaga, let’s start asking why they didn’t fully understand what they were signing up for, and how we can fix that.
The future of financial health depends not just on the products we build, but on the knowledge we provide.