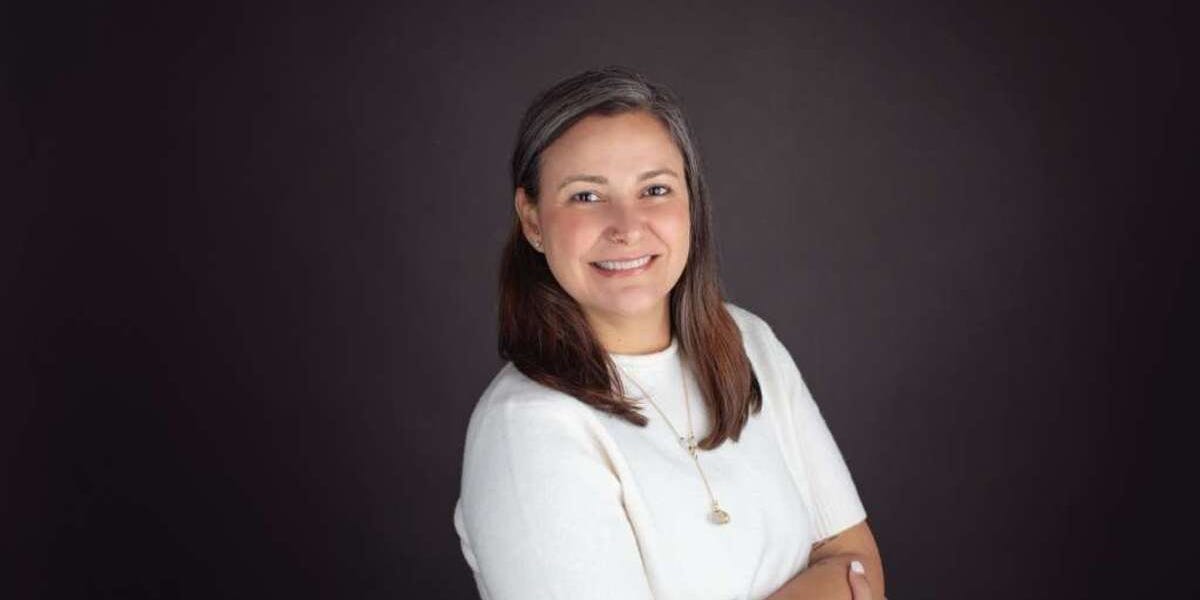
This as-told-to essay is based on a conversation with Michelle Gudiño Prestamo, a 41-year-old human resources manager at a major footwear company in Mississippi. The following has been edited for length and clarity.
I serve as the human resources manager at a distribution center for a major footwear brand. I joined the company in 2019. Prior to this role, I worked at a staffing and recruitment firm where I provided support to footwear and retail clients.
I have no intention of working well into my eighties. My goal is to retire at 65 and launch my own coffee shop, something I’ve always been passionate about. Here’s how I’m working toward that future.
I was born in Venezuela.
I relocated to the United States in 2009 through a cultural exchange program as an au pair. I resided with a host family in Germantown, Tennessee, for nearly two years. During that time, I worked full-time as an au pair while also studying English and human resources management.
I met my husband in 2010, and we tied the knot in 2013. I became a U.S. citizen in 2019. The U.S. offers countless opportunities, resources, and pathways to homeownership and vehicle ownership. However, it also presents significant financial temptations.
While others struggle with alcohol or gaming, my challenge was overspending. I used shopping as a way to express affection — buying gifts for loved ones and souvenirs during travels.
At its peak, I carried more than $55,000 in credit card debt.
At one time, I held 10 different credit cards. I attempted to tackle the debt independently, but soon realized I needed professional guidance. Through my employer’s employee assistance program, I discovered several support services, including Money Management International.
Before getting assistance, my debt continued to grow due to mounting interest charges. With expert help, I restructured my budget and broke free from the cycle of living paycheck to paycheck.
Throughout the three-year repayment program, my monthly obligation was $1,077. In some months, I contributed extra payments using bonuses from work.
In April, I officially paid off all my credit card debt.
My spouse and I also own a home.
My husband runs his own restaurant and covers the mortgage payments with his business income. Since we don’t combine our finances, my credit card debt was entirely my responsibility. My parents also live with us, along with our son, who will turn 6 in December.
After renting for some time, I encouraged my husband that we should purchase our own home. We applied for a mortgage, received approval, and relocated to Olive Branch, Mississippi — a Memphis suburb — in 2018. The house is just minutes from my workplace, and we’re steadily building equity.
My employer offers a 401(k) plan with a 6% matching contribution.
Until April, I had been contributing only 2% of my income to the company’s 401(k) plan. Once I cleared my credit card debt, I boosted my contributions to the maximum matched amount of 6%. I may raise it further in the coming months. I constantly set new milestones for myself.
My current objective is to accumulate one month’s salary in a dedicated “buffer” checking account — ideally two months’ worth — and avoid dipping into it. I intend to use upcoming bonuses to fund this emergency reserve. Due to my previous debt burden, I hadn’t been able to build an emergency fund until now.
Ultimately, I aim to save six months’ salary in an account at a local credit union. I’m taking things one step at a time. I’ve also opened a separate savings account for my son at the same credit union.
Having clear goals makes all the difference.
I rely on vision boards for both personal and professional aspirations. Staying consistent and defining exactly what you want is crucial. I reflect on past setbacks and mistakes to grow stronger.
Currently, my focus is on developing and maintaining healthy financial habits. I track every expense using an app, I’ve reduced the number of credit cards I use, and I pay off balances monthly. Occasionally, I feel anxious — but that fear motivates me to push harder toward my targets and recalibrate them when necessary.
I’ve been with this company for seven years. I have no desire to fall back into debt. I’m not getting any younger. I enjoy my job — its responsibilities, compensation, and benefits — but I’m eagerly anticipating retirement.